For Sale
$000,000
[123 Example Street, City, CA]
- 0 beds
- 0 baths
- 0,000 sq ft
Santa Clarita · San Fernando Valley
The numbers first. Then the house.
REALTOR® · CA DRE# 02200933 · Next Real Estate Group
Start here
No pressure and no credit pull. Tell me where you are and I'll come back with the loan programs and assistance that fit your situation, including the ones most buyers never hear about.
If the right answer is "wait six months and fix these three things," I'll tell you that too.
Prefer to talk? Call or text (818) 381-1844.
Takes about a minute. I reply within one business day.
One email or phone number is enough. Your information is never sold or shared.
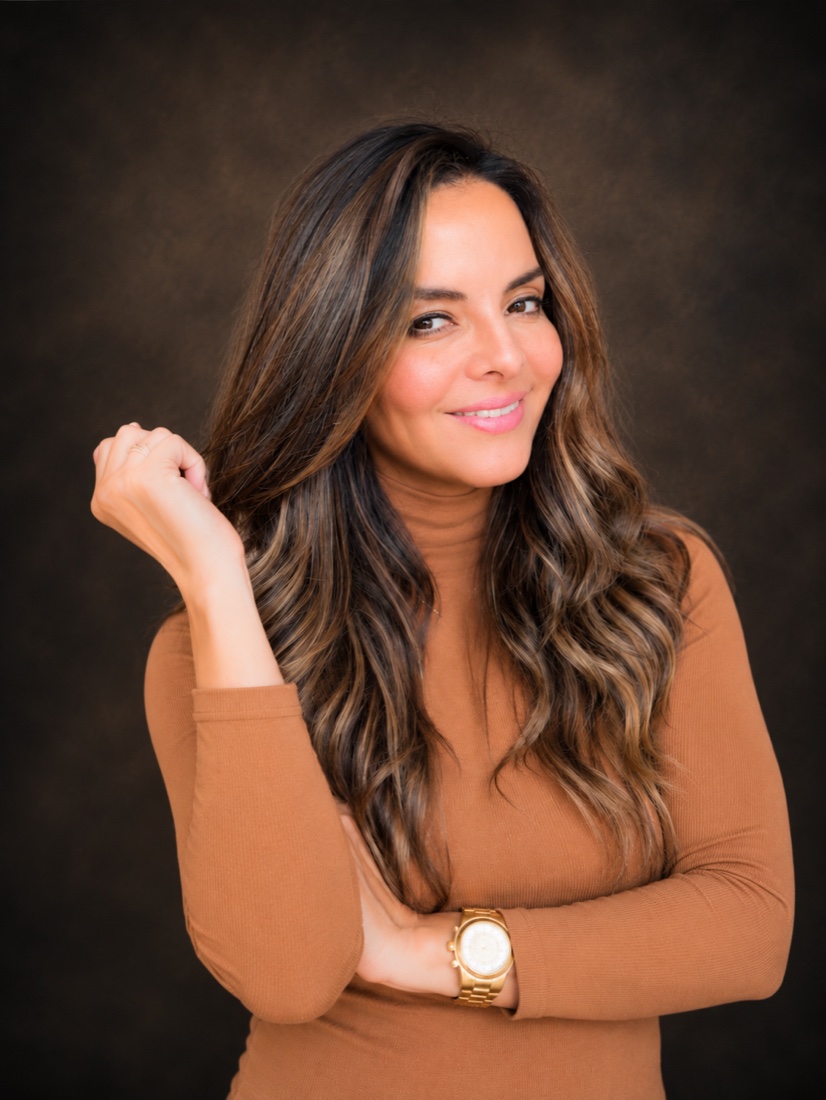
Vania La Hoz · Next Real Estate Group
About
I live in Santa Clarita, and I work throughout the San Fernando and Santa Clarita valleys, up into the Antelope Valley to Palmdale and Lancaster, and anywhere nearby my clients are looking. That matters more than it sounds. When you ask me about a street, a school boundary, a Mello-Roos district, or what the 5 actually looks like at 7am, you get an answer from someone who drives it, not someone reading it off a listing sheet.
I work at Next Real Estate Group, a boutique brokerage in Mission Hills owned and led by women who built it themselves. Boutique is not a style choice here. It means you are not a file passed between assistants: the person who answers your first message is the person who writes your offer, sits through your inspections, and picks up the phone when escrow sends something at 8pm that makes no sense.
Most of the real work happens before anyone tours a house. People come to me certain they need 20% down, or that assistance programs are only for very low incomes, or, if they are 55, that they have to wait until 65 to move without losing their property tax base. All three are wrong, and all three cost real money. I would rather spend an hour making sure the numbers make sense to you than sell you something you regret in a year.
That comfort with numbers is not an accident. I hold a bachelor's degree in business, and before real estate I spent years in banking and insurance, explaining financial decisions to people who were making them for the first time. A mortgage, a property tax base transfer, a down payment assistance program: it is the same conversation in a different room.
I am a mother of two, so I understand that a house is a decision about commutes, schools, and what your Saturdays look like, not just square footage. I work in English and Spanish, because the family making this decision is often larger than the two people signing, and because the person with the hardest questions is sometimes the one least comfortable asking them in English. I am originally from Peru, and I have lived in California for more than half my life.
Where do you fit?
The right strategy depends entirely on which of these you are. Pick yours.
The belief that you need 20% down keeps more Californians renting than any other single idea. Loans start at 3% down, and assistance programs can cover much of that.
Get pre-approved by a lender who actually handles assistance programs. Many loan officers don't, and will quietly steer you away from money you qualify for rather than admit it.
Ask the question directly: "Do you originate CalHFA and local down payment assistance loans?" The answer tells you everything.
Proposition 19 lets eligible homeowners carry their assessed value to a replacement home anywhere in California, up to three times, even if the new home costs more.
A homeowner assessed at $200,000 who buys a replacement home at $850,000 keeps paying on $200,000, roughly $2,200 a year instead of $9,350.
Illustration at a 1.1% effective rate. Your rate, exemptions, and local assessments change the result.
Business owners and contractors reduce taxable income, and then that lower income is exactly what the lender sees. Strong businesses get declined for this reason every day.
Talk to your CPA and a loan officer in the same conversation, two tax years before you want to buy. Easing off deductions for one or two years can qualify you for a conventional loan and save far more in interest than the write-offs saved in tax.
Most sellers here are also buyers, and the order of the two transactions changes your taxes, your financing, and your negotiating position.
If you plan to buy again in California and you are 55 or older, model the Prop 19 transfer first. The numbers can favour buying before selling, and once you are in escrow, that option is gone.
Guides
Price tags get all the attention. These are what actually move your monthly payment and your out-of-pocket cash.
Conventional, FHA, VA, USDA, jumbo, and self-employed options, what each one costs you and who it's built for.
Compare loans →
State and city programs that cover part of your down payment. Many buyers qualify and never apply.
See assistance programs →
Prop 13, the supplemental bill nobody warns you about, and how buyers 55+ can carry their low tax base to a new home.
Understand CA taxes →
Pre-approval to keys, with real timelines and an honest list of your closing costs.
Walk through it →
2026 numbers
Conforming loans have easier terms and better rates than jumbo loans. Here is exactly where that line falls in the two counties I work.
| County | Conforming | FHA |
|---|---|---|
|
Los Angeles Santa Clarita, the Valley, Burbank, Glendale |
$1,249,125 | $1,249,125 |
|
Ventura Simi Valley, Moorpark, Thousand Oaks |
$1,249,125 | $1,249,125 |
| National baseline, for comparison | $832,750 | Lower in most counties |
Both of our counties sit at the national ceiling, the highest limit in the country, and FHA matches it exactly. That is unusual, and it works in your favour: most purchases in Santa Clarita, Granada Hills, Northridge, Reseda, Burbank, or Simi Valley stay comfortably inside conforming territory, with the easier terms and better rates that come with it.
You cross into jumbo in the pricier pockets, Sherman Oaks, Encino, Studio City, Toluca Lake, Calabasas, and the hillside streets. If your purchase lands anywhere near $1.25M, run the numbers both ways before writing the offer.
Properties
A short, honest list beats a padded one. These cards are placeholders until your MLS feed is connected.
$000,000
[123 Example Street, City, CA]
$000,000
[123 Example Street, City, CA]
$000,000
[123 Example Street, City, CA]
Often missed
California's Proposition 19 lets eligible homeowners age 55+ carry the assessed value from their current home to a replacement home anywhere in the state, up to three times. For someone who has owned since the 1990s, that can be the difference between a property tax bill of a few thousand dollars and one of twenty thousand.
It applies at 55, not 65, a detail that costs people years of savings because they assume they have to wait.
A homeowner with a $180,000 assessed value sells and buys a replacement home for the same price or less.
| Assessed value kept | $180,000 |
| Approx. annual tax at ~1.1% | ~$1,980 |
| Without the transfer, on an $850,000 purchase | ~$9,350 |
Illustration only. Your rate, exemptions, and any local assessments change the result.
Clients
[Placeholder testimonial. Replace with a real client quote, what they were worried about, and what actually happened.]
[Client name, city]
[Placeholder testimonial. Specifics beat praise: a program they didn't know existed, a number that surprised them.]
[Client name, city]
[Placeholder testimonial. A first-time buyer story works well here.]
[Client name, city]
Next step
Send me your details and I'll come back with the loan programs and assistance you may qualify for in your county. If the answer is "wait six months and do these three things," I'll tell you that too.
Prefer to talk? Call or text (818) 381-1844.
Takes about a minute. I reply within one business day.
One email or phone number is enough.